

Every Sunday I pick the China tech stories that mattered that week, say what I make of each, and link back to where I first wrote about it. Subscribe free
From Nvidia’s leadership change to China’s chip fabs, cloud units and robot startups, this week’s stories landed on one ledger: who absorbs the cost of China’s AI buildout. Five events showed how Chinese tech firms and investors are splitting that bill across silicon, staff and models.
Jensen Huang’s exit puts pressure on Chinese chipmakers.
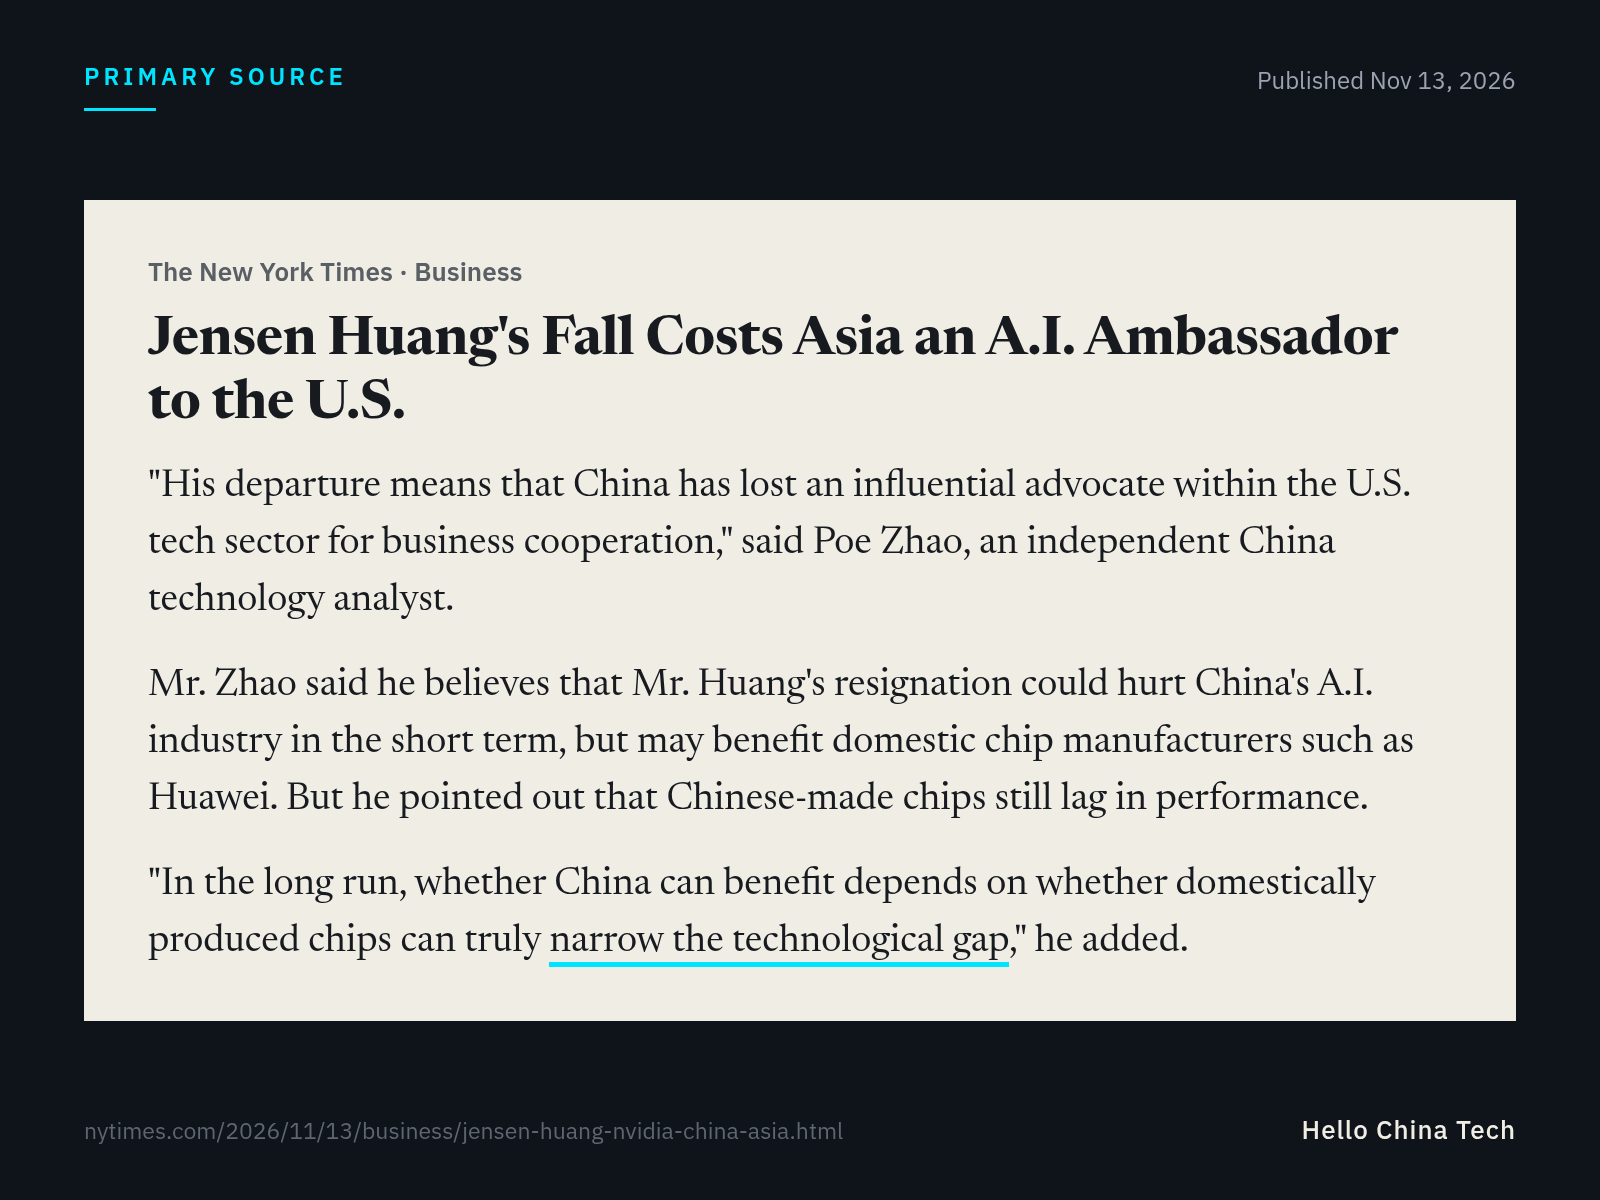
Nvidia CEO Jensen Huang resigned, and The New York Times reported on November 13 that his exit could accelerate Beijing’s drive toward chip self-sufficiency. The paper quoted me on the boundary: “In the long run, whether China can benefit depends on whether domestically produced chips can truly narrow the technological gap.” In my view, Huang’s departure pushes Chinese demand toward local silicon faster than manufacturing capacity and training software can move. In October, I wrote about where Huawei’s AI chips still trail Nvidia’s in iFlytek’s own testing.
SMIC’s profit doubled, yet partners took a third.
On November 12, SMIC, China’s largest contract chipmaker, reported third-quarter revenue of $3.19bn, up 33.9% year-on-year, according to China Finance Information. Total profit under international accounting standards doubled to $651m, The Paper reported, yet $223m, or 34.3%, went to minority shareholders in SMIC’s subsidiaries. I read SMIC’s consolidated statements as the top layer of a rotating fab-financing structure. This week I worked through how state funds share SMIC’s subsidiary fab profits even after a major buyout.
Alibaba confirmed its chip unit’s Hong Kong filing.
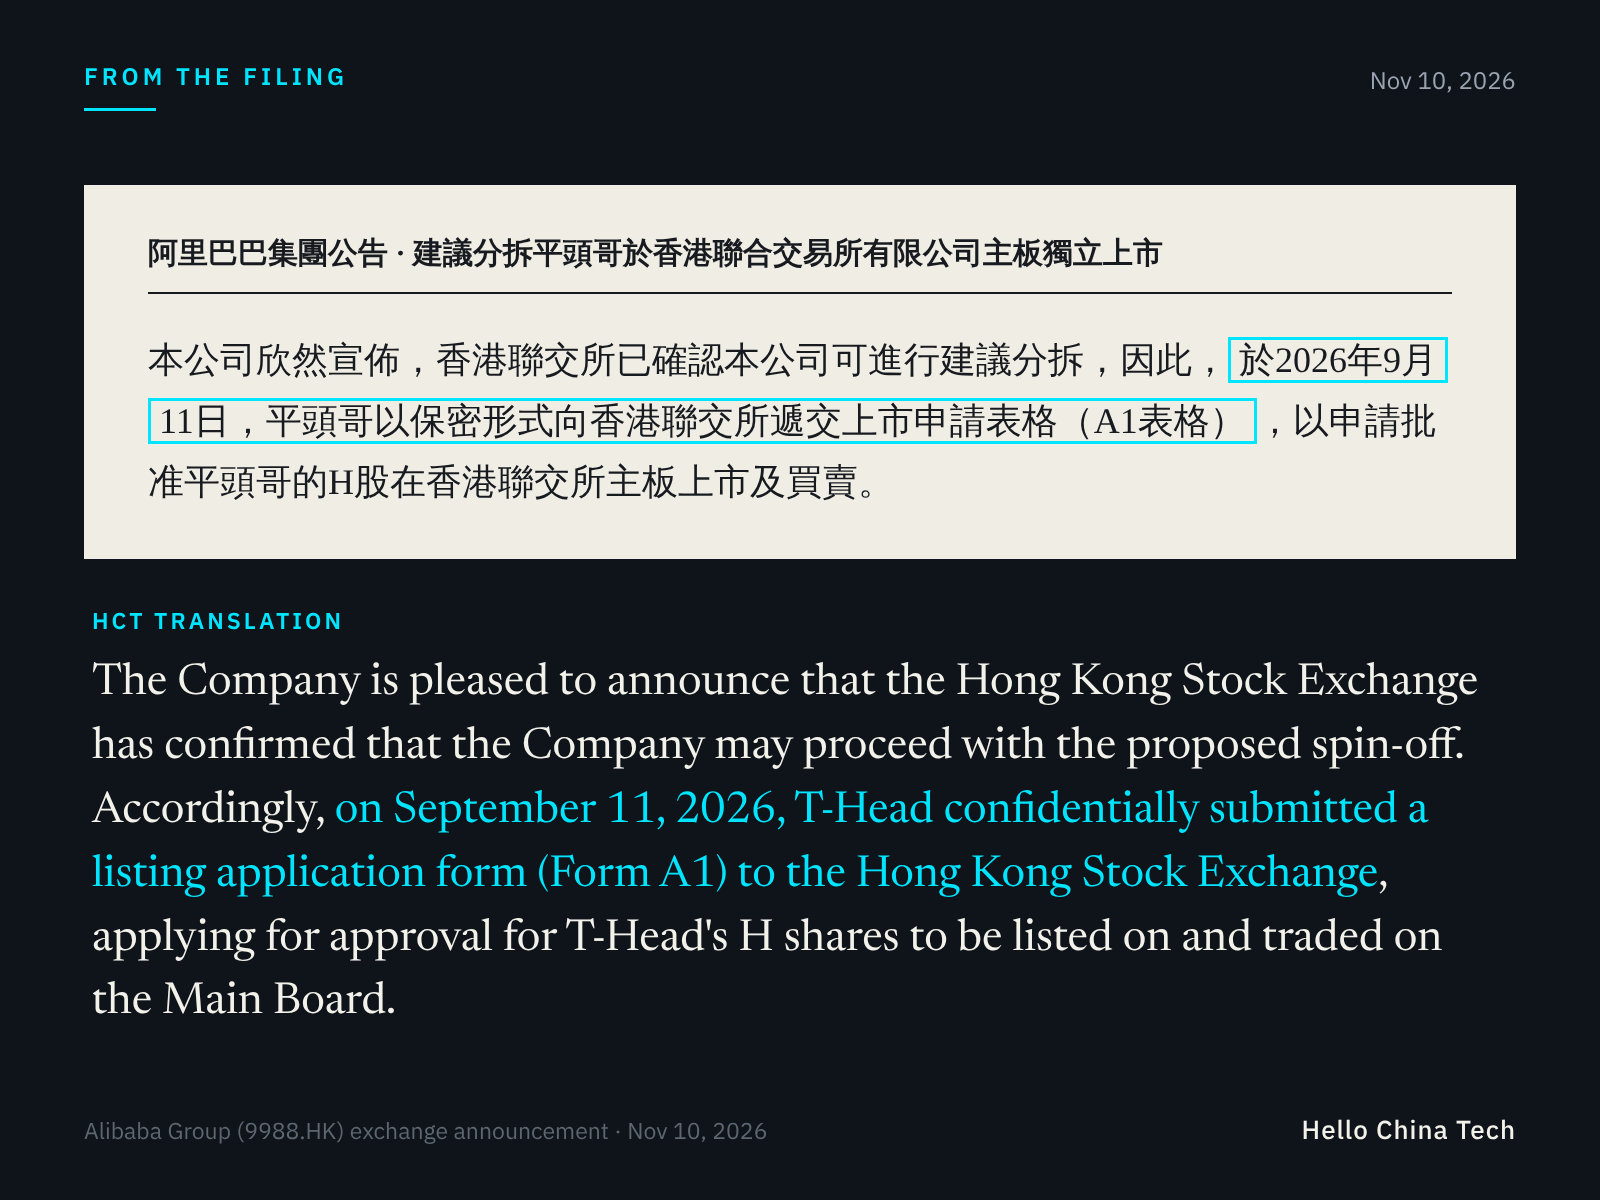
Alibaba announced on November 10 that T-Head, its in-house chip unit, filed confidentially on September 11 to list H shares on Hong Kong’s main board. The announcement describes T-Head as a leading full-stack data center chip supplier in China and says the offering still needs listing-committee approval, a securities-regulator filing and final company decisions. If a prospectus appears, I expect it to reveal how much of T-Head’s revenue comes from Alibaba itself. That goes back to my September piece on why Alibaba’s 20-gigawatt cloud target rests on unpublished T-Head numbers.
Tencent split its staff into an army and a navy.
At Tencent’s 28th anniversary broadcast, management said 50% of staff should act like the army in core businesses and 50% like the navy exploring AI Native, Chinese outlet The Paper reported on November 12. A person close to Tencent denied rumors of 50% layoffs, calling the talk a misreading of resource reallocation. I see that internal split as the organizational version of the two-book valuation pitch management gave analysts earlier this year. My August analysis tracked how Tencent asks investors to separate its core franchise from AI.
Anthropic tested a general model on robot control.
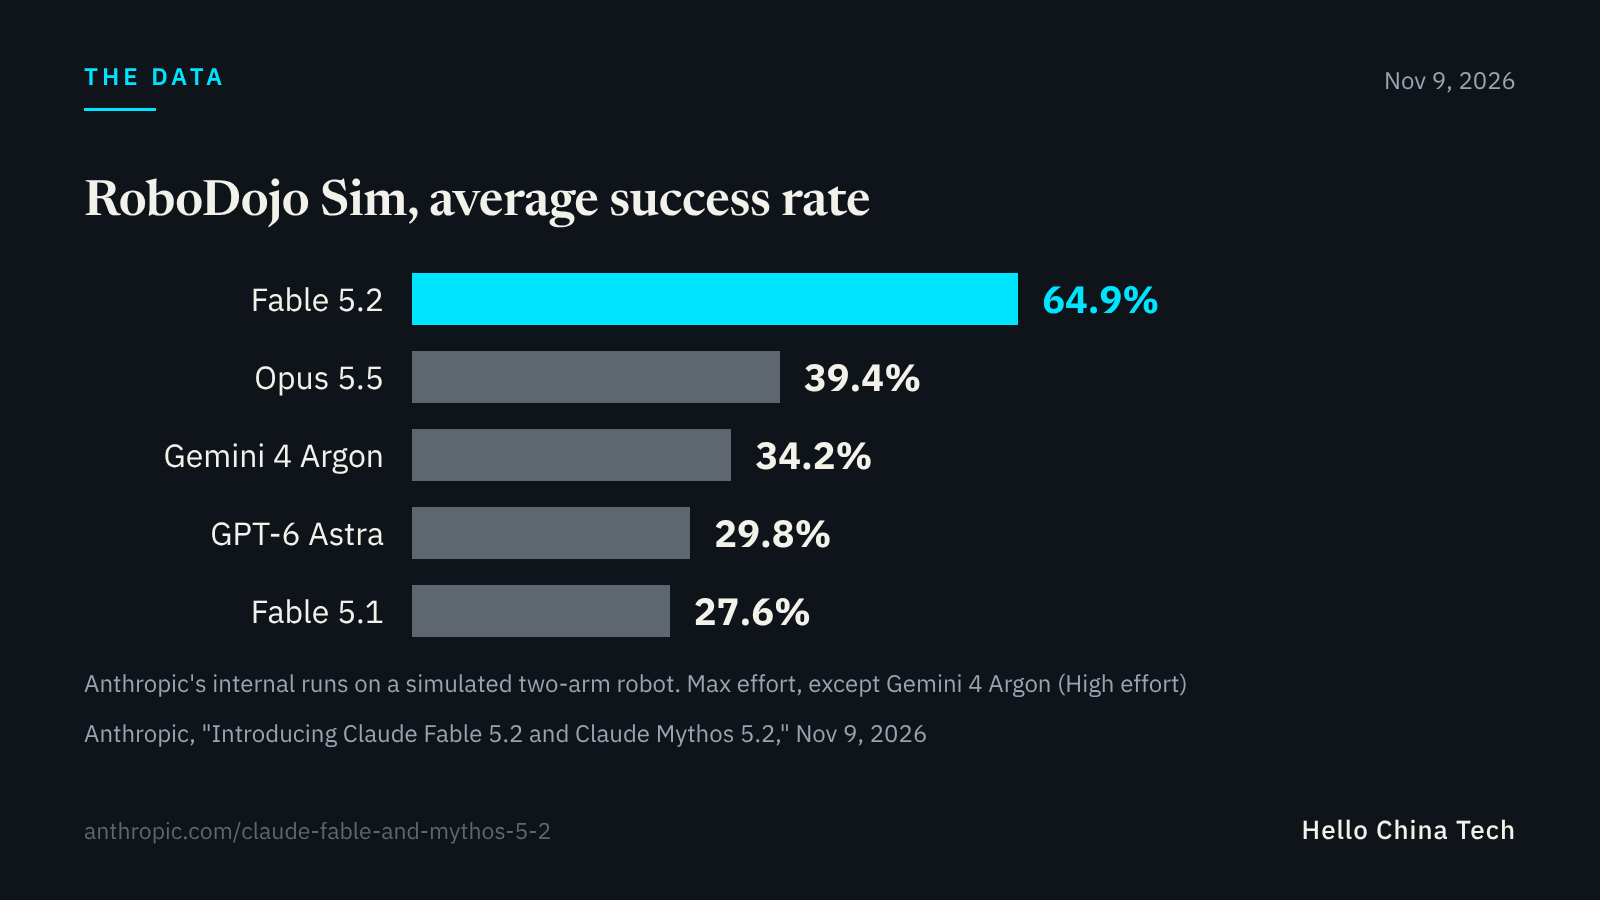
Anthropic released Claude Fable 5.2 on November 9, reporting that the model scored 64.9% on RoboDojo Sim in its own internal runs at Max effort, more than double OpenAI’s GPT-6 Astra at 29.8%. Anthropic says Fable 5.2 outperformed most AI systems built specifically to control robots on that simulated two-arm benchmark. I would expect Chinese robot startups priced on proprietary models to face sharper investor questions in their next private rounds. I counted five Chinese robot startups priced on models rather than shipments back in August.
ALSO THIS WEEK
World Models and China’s Humanoid Certification Gap: Why China’s autonomous-driving rules still require road miles while humanoids lack tests.
How to Read China’s AI App Numbers: Five checks for reading monthly users and total sessions across Chinese AI apps.
China’s AI Drug Platform, Priced Like a Pipeline: How Baidu-backed BioMap structures drug milestone deals ahead of a Hong Kong listing.
Next week, Baidu, Tencent and Alibaba report quarterly earnings. I will be watching what their numbers and calls show across models and chips.
$150/year, or $20/month. You can also buy any single piece at the end of its free preview ($5 for a deep dive, $3 for a FlashPoint).
Poe
Good ledger — and the line item that rarely gets priced in is the power bill. Alibaba's 20 GW cloud target is the number to sit with: at data-center scale, 20 GW is roughly twenty-plus large hyperscale campuses, and the power has to be firm, not just contracted. That's why the buildout is drifting toward where the energy is — Inner Mongolia's wind and solar hubs, with storage doing the firming — rather than where the users are. SMIC's side of the bill is similar: fabs are among the most power-hungry industrial loads, and the 34% minority share shows how much of the economics now sits in the financing structure, not the wafer. The question 'who pays' will increasingly be answered in megawatt-hours, not just yuan. We track the Chinese suppliers building the power side of this stack — inverters, storage, switchgear — from the factory floor up.